Ceiling water damage insurance documentation in Duarte, CA is mostly about proof of timing, cause and scope. An adjuster is not at your house when the water arrives, so photos, readings and receipts have to tell the story. A leak from an upstairs fixture, the attic or the roof is a common claim, and the better the record, the fewer arguments about what happened and when.
This guide is general information, not legal advice or a promise of coverage. Policies differ, so read yours and ask your insurer what applies to your loss.
What coverage usually turns on
The California Department of Insurance explains that homeowners policies do not cover flood, but they do cover other kinds of water damage.
Coverage depends on cause. Sudden and accidental water damage, such as a pipe that bursts or a roof opening during a storm, is often covered. A leak that dripped for months or came from neglected maintenance is often not. For that reason, your records should show when you first saw the problem and how fast you acted.
The CDI also says to report any water damage claim immediately to your agent or company. Do that before repairs go beyond what is needed to protect the home.
Your duty to protect the property
Most policies expect you to take reasonable steps to prevent further damage, and CDI notes that an insurer may not pay for added damage if you did not secure the property. The insurer will generally reimburse reasonable costs to protect your property, so temporary repairs are worth doing and worth recording. That can mean shutting off water, tarping a roof, moving belongings and starting water damage cleanup with drying equipment.
Keep every receipt. Store them in a folder or photograph them the same day. Tarp rolls, plastic sheeting, fan rentals and emergency service invoices all belong in the claim folder.
Why moisture mapping matters to an adjuster
A stain on the ceiling shows only one surface. Moisture mapping records readings across the ceiling, walls and floor on a sketch, and repeats them on later visits, so the file shows how far the water traveled and when each material dried. It turns a debate about how much to repair into a record of what was wet.
Thermal camera images help because they show wet insulation and framing without opening the ceiling. A pin meter then confirms the reading at specific spots. Ask the crew to date every reading, note the instrument used and to label the room, because readings without dates and locations carry little weight.
The documentation checklist
- Date and time log. Write when you noticed the stain, what you did and who you called. Include the weather if it rained.
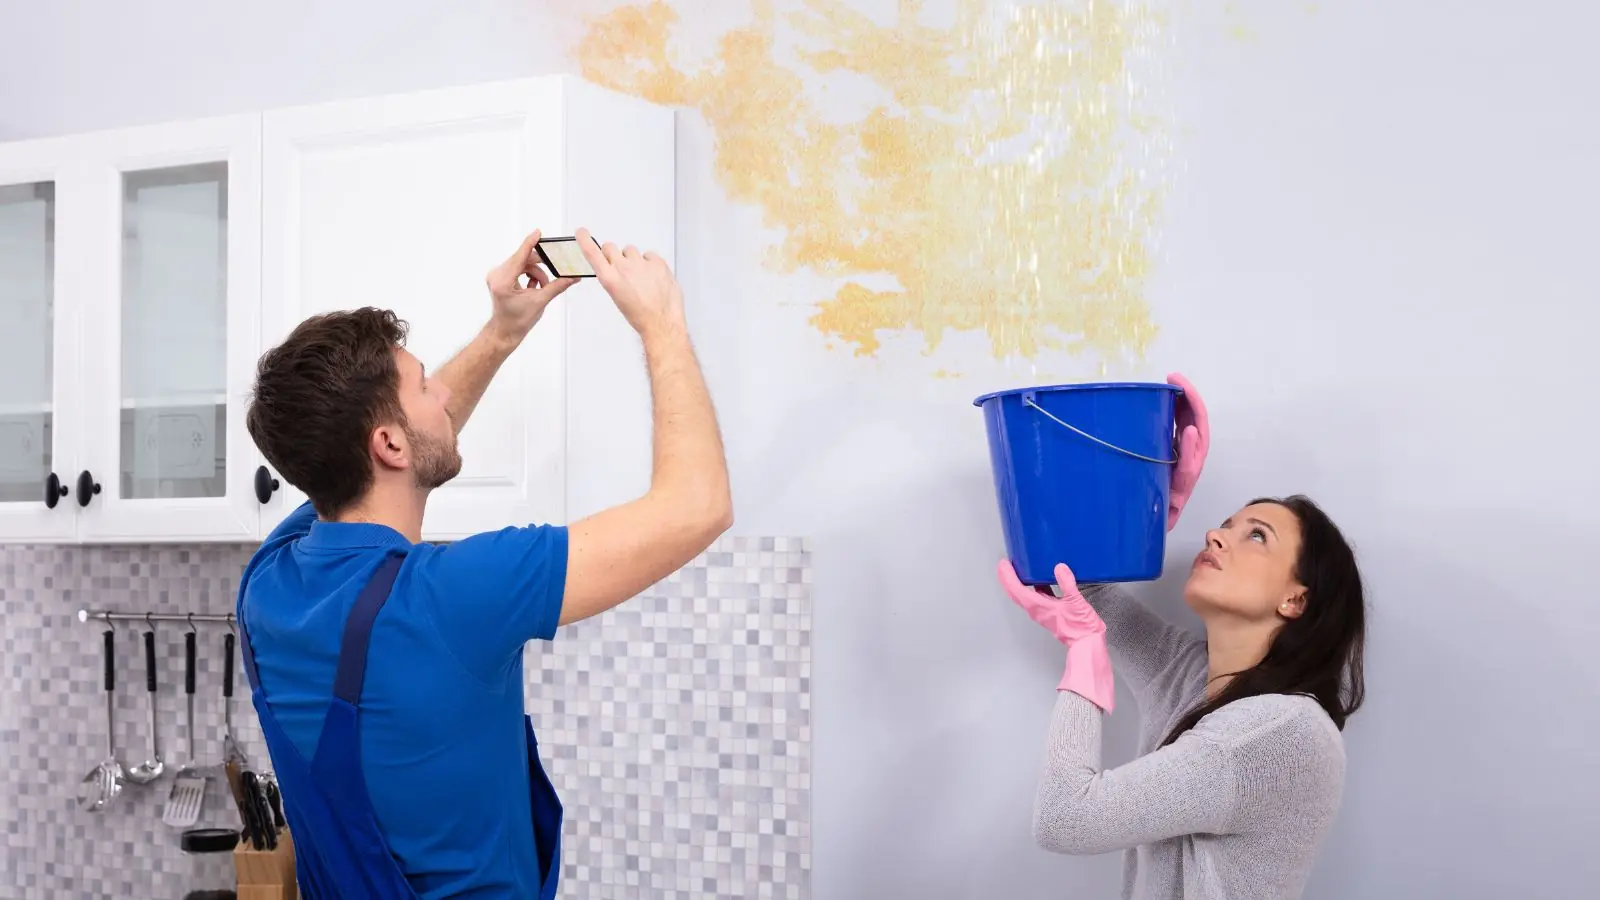
- Wide, medium and close photos. Take them of every wet ceiling, wall and floor, plus the room's overall condition. Keep originals with timestamps.
- Video walkthrough. Narrate what you see and where, including the attic or floor above if safe to enter.
- Photos of the source. Capture the failed fixture, pipe, flashing or hole before it is repaired, and keep the failed part if you can.
- Moisture readings. Ask the crew to record meter readings and thermal images at the start and each visit until dry.
- Moisture map. A sketch of the affected rooms with wet areas marked shows scope better than words.
- Written scope of work. It should list materials removed, equipment placed, monitoring visits and what remains to be repaired.
- Receipts and invoices. Include plumber, roofer, restoration and rental items. Photograph paper receipts so they cannot fade.
- Inventory of damaged belongings. List item, age, approximate value and photo. Keep damaged items until the adjuster has seen them, unless they are a health hazard.
- Communication record. Note claim number, adjuster name and every call or email with dates.
Need readings and photos for your claim?
Call the 24/7 line to start emergency drying. Ask the crew to record moisture readings, thermal images and a written scope at the first visit so your adjuster has them.
Mold after a ceiling leak
If you suspect mold after a leak, CDI advises contacting your adjuster immediately, because mold caused by a covered peril may be covered. Do not scrub or disturb it first. Note it in your log, photograph it and ask the restoration company how it follows ANSI/IICRC S520 practice. Mold needs moisture, so drying is the first control, and health questions go to a physician.
Keeping the file tidy
Create one folder, on paper or on your phone, and put everything in it from day one. Back up photos to a second location, since phones get lost and cracked. If you speak with the adjuster by phone, send a short email afterward confirming what was said, which gives you a dated record.
Do not start permanent repairs until the adjuster has had a chance to inspect or has told you in writing to proceed. Temporary protective steps are different, and your policy expects them. When in doubt about the line between the two, ask your insurer before you spend money on rebuilding. A crew handling water mitigation can keep drying logs that match your claim file.
What not to assume
Do not assume the first estimate is final, that a company's invoice equals a covered amount, or that a repair will be approved because it looks obvious. Insurers set their own time limits under California's Fair Claims Settlement Practices Regulations. If you feel a delay is unreasonable, ask your insurer to explain in writing, and contact the Department of Insurance if you need help.
Duarte local note: owners and renters have different files
Census figures put Duarte at 7,515 households, with about 61 percent owner-occupied, which means roughly four in ten households rent. That changes who files what. An owner usually files under the homeowners policy for the building and contents. A tenant usually has a renters policy for belongings only, and the landlord's policy handles the structure.
If you rent, tell your landlord in writing the day you see the leak and attach photos, then check your own renters policy for belongings and displacement costs. If you own, call your agent first. Either way, your moisture readings and daily log are worth more than your memory of the date.
Sources: Census, CDI
Nearby utility records
Water bills can help show when a hidden supply leak started. In Azusa, the city-owned Azusa Light & Water serves some neighboring areas, and in Glendora the City Water Division handles service, so ask your utility for a usage history that matches the dates of your damage.
Questions Duarte homeowners ask
Call as soon as it is safe, and do not wait on the adjuster to begin emergency steps. CDI says to report water damage claims immediately and to take reasonable steps to protect the property. Document each step with photos and receipts.
It depends on the policy and the cause. Sudden and accidental storm damage is often covered, while wear, neglect or slow leaks often are not. Ask your insurer to explain the exact policy language that applies.
Readings show how far the water spread and when materials returned to dry. They also support the written scope, since they prove which drywall and insulation needed removal instead of leaving that to opinion.
Keep photos of everything, and keep samples or ask your adjuster before throwing away large items. Mold-affected or unsafe material should be handled by a professional and photographed first.
With roughly 39 percent of Duarte households renting, this comes up often. The landlord's policy usually covers the building, and your renters policy covers your belongings. Notify your landlord in writing right away and check your own policy for displacement costs.
Usually not. CDI says standard homeowners policies exclude flood, and a separate flood policy is needed. Ask your insurer which type of water your policy treats as covered.